

Navigating the mortgage market can feel overwhelming, particularly when deciding between a fixed or variable interest rate. Fixed rates offer stability and predictability, while variable rates provide flexibility and the potential to save if rates fall. Fortunately, split loans allow borrowers to combine the benefits of both, offering a solution that balances security with adaptability.
A split loan divides your mortgage into two portions. One portion is locked into a fixed interest rate, ensuring your repayments remain stable regardless of market movements. This is particularly beneficial for those who value certainty in their budgeting or want protection from rising interest rates. Fixed rates make long-term planning easier, especially if you have significant expenses on the horizon, like a holiday or renovations. However, it’s important to note that fixed loans often come with limitations. Many restrict how much extra you can repay during the fixed term and exclude features like offset accounts. Additionally, exiting a fixed loan early can result in significant break costs, so this needs to be carefully considered.
The other portion of a split loan is placed on a variable interest rate. Unlike fixed rates, variable rates fluctuate with the market, meaning your repayments can rise or fall depending on economic conditions. Variable loans are known for their flexibility, offering features like offset facilities that can help you reduce the interest you pay or access surplus funds if needed. They also allow unlimited extra repayments, which can be a powerful tool for paying off your mortgage faster. While variable rates provide the potential for savings if rates drop, they also carry the risk of higher repayments if rates rise, making budgeting more challenging.
By splitting your loan, you get the best of both worlds. The fixed portion provides peace of mind, ensuring you’re shielded from sudden rate hikes, while the variable portion allows you to take advantage of features and potentially lower rates. This approach is particularly appealing in uncertain economic climates, where interest rate movements are difficult to predict. For example, if rates rise, your fixed portion protects you from the full impact, and if rates fall, you can still benefit through the variable portion.
Choosing the right split for your needs is key. Some borrowers may prefer a 50/50 division, while others might lean more heavily toward fixed or variable, depending on their financial goals. It’s also worth noting that split loans are gaining popularity, with recent trends showing a growing number of borrowers opting for fixed rates as they become more competitive compared to variable rates.
In summary, a split loan can offer a balanced approach to managing your mortgage, combining the stability of fixed rates with the flexibility of variable rates.
By understanding your financial goals and working with a mortgage broker, you can tailor your loan to suit your needs and navigate the complexities that often come with choosing your loan product. If you would like our advice on whether a split loan would be right for you, get in touch and we can work through the details with you.
Written by Matthew Edginton, Finance Broker – AP Group
AP Group are the leading pharmacy experts in Australia and specialise in helping first time buyers find the right pharmacy and secure the finance to support their purchase.
We connect existing owners with over 5000 ready and eager investors via our cutting-edge online Data Room. Our Data Room keeps confidential listing data secure and allows buyers to make informed decisions on each of our pharmacies for sale.
AP Group have built connections with all the major banks and a host of smaller lenders, ensuring that first time pharmacy buyers find a better deal.
About the Author:
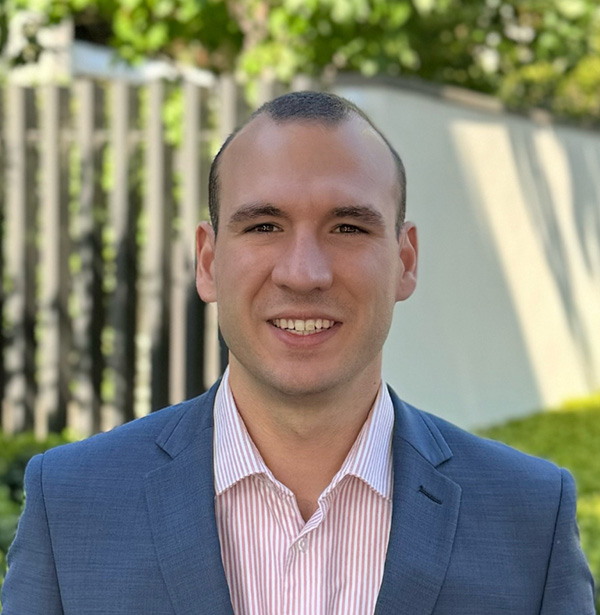
Matt is a solutions guy. Whether it’s training his two sausage dogs (Sassy and Lenny), learning different plant varieties, or helping his clients with complex lending — he enjoys being presented with a challenge and finding ways to overcome it. His finance journey began in 2018 when he moved to Melbourne from Adelaide (some might also say this was for better access to AFL).
Before joining AP Group, Matt trained as a mortgage broker with one of the largest construction finance brokers in the state. He worked closely with several experts in the field – setting him up with the knowledge, experience and skillset he has today.
For Matt, he loves the combination of complex finance work and giving excellent customer service. He’s personable, dedicated and responsive, working tirelessly to find finance solutions to help you achieve your goals.